Most foreign buyers assume the building is already insured and that this covers them. The association's policy and the owner's own policy cover different things, and between the two sits a gap that shows up on the day of a loss.
The association's policy covers the building's common property and the administrador takes it out against the budget; the owner's policy covers the private area, the contents and third-party liability, and you take that one out. For a serviced lot the boundary between them does not fall in the same place, and that is the exposure: what is bien común de uso exclusivo for one unit is private area for another, and a terrace, a boundary wall or an air-conditioning unit can end up outside both policies. Where there is a mortgage the lender also requires its own cover as a condition of disbursement, and charges it inside the instalment. Before signing any of them, confirm with the Superintendencia Financiera that the insurer is supervised, and before insuring anything, find out what risk information the District holds on that property.
A serviced lot is bought differently because what you acquire is a capacity to build, not a built thing. The value sits in what the rules allow on that specific parcel and in the state of the surrounding development, not in what you see on a site visit, which looks much the same on every lot of the block. Three consequences follow. First, the folio tends to be young, since it was created by splitting a larger parent parcel, so the useful history lives in that parent folio and in how areas, roads and public land dedications were divided. Second, the developer does not vanish with the sale: if water, sewer, road or green- area works are still unbuilt, or obligaciones urbanísticas (duties owed to the city by the developer) are still outstanding, there remains a counterparty, and it is worth knowing who answers for them and against what security. Third, the asset produces nothing until it is built on, while still generating impuesto predial, development dues and the cost of watching over empty land. For a buyer abroad, a lot also means a permit process and a construction job run from Colombia, by someone authorized to sign.
What you buy in Morros is not land but a private unit created by subdividing a single folio matriz, the parent registry record, and that changes the file. The chain of title on the land was settled once by the builder; what remains to review is the registered reglamento de propiedad horizontal, the condominium bylaws, any acta de asamblea, owners' meeting minutes, that amended them, and the coeficiente de copropiedad, the ownership share assigned to the unit, which governs both voting and billing. The counterparty differs from the undeveloped north as well: usually an individual owner living outside Cartagena, so closing depends on a power of attorney from that person, on a spouse's consent where it applies, and on the paz y salvo, a no-arrears certificate signed by the building manager, a document that does not even exist for rural land. Decisions here belong to the owners' assembly and the manager it appoints, not to a public office; the District and the curaduría urbana, the private licensing office, had their say when the tower was permitted. Internal infrastructure, from pumping to the generator and security, is private and funded by the budget that same assembly approves, so the minutes describe the property better than any tour.
What is specific to Morros
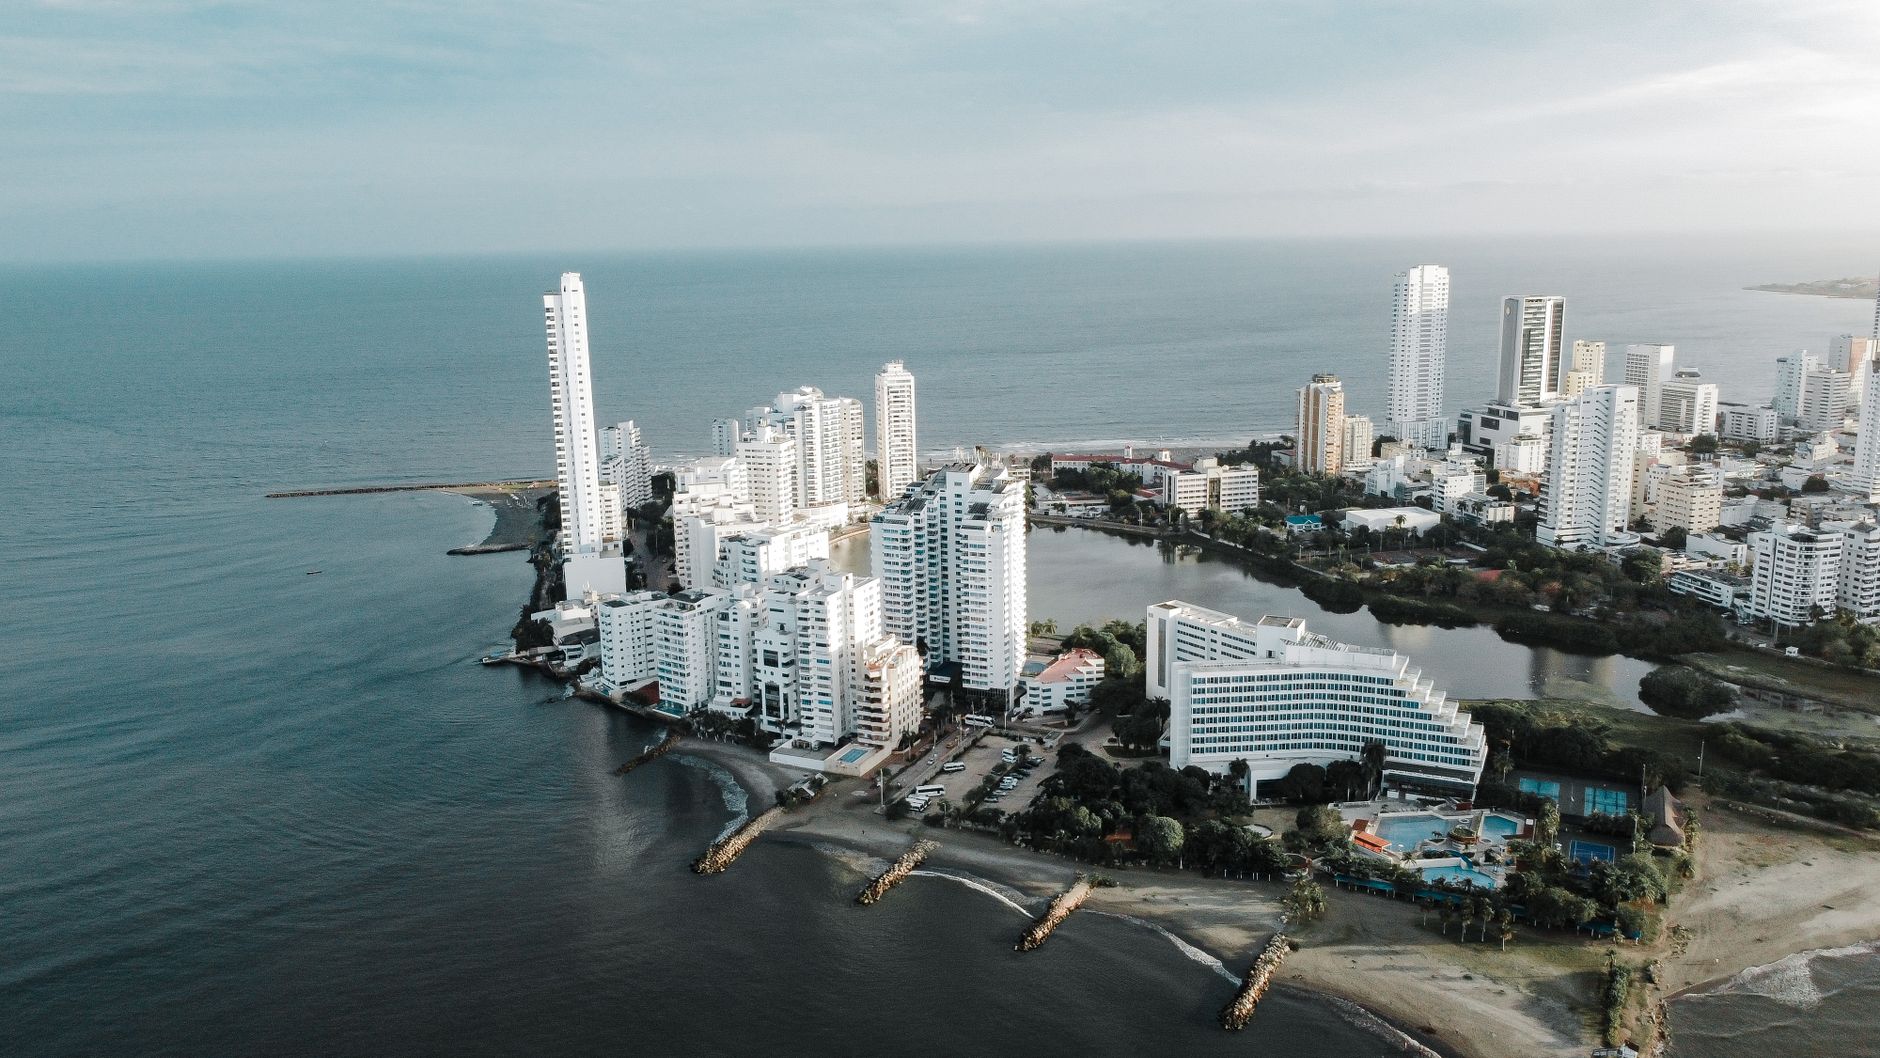
The first consolidated stretch of the Zona Norte: gated tower complexes along the road, beach in front and their own amenities. Almost everything is high-rise condominium, much of it bought as a second home and rented out seasonally. It sits minutes from the airport along the Anillo Vial, which is its only real way in and out.
- what the condominium bylaws say about daily rentals, because several complexes restrict them and buyers find out after signing
- the state of the maintenance dues and the reserve fund, which in seafront buildings goes into façade upkeep
- whether the tower holds a concession or permit for the beach in front, which does not come with the apartment
What to verify, step by step
- Ask the administrador for the current certificate of the association's policy, with its cover, exclusions and the insurer's name.
- Ask for the reglamento and the deed so you know where the unit's private area ends and common property begins, which is the line that decides which policy responds.
- Verify with the Superintendencia Financiera that the insurer and the intermediary are supervised before paying any premium.
- Review what has to be insured because it is serviced lots: whether the lot has been split out with its own matrícula inmobiliaria or still sits inside a larger undivided parcel; what the rules let you build on that specific lot —use, height, setbacks, ground coverage— and whether the licencia de urbanismo is current and which obligaciones urbanísticas (developer duties owed to the city) are still outstanding and whether they pass to the buyer, since they fall due before you can build.
- Add the exposures particular to Morros: what the condominium bylaws say about daily rentals, because several complexes restrict them and buyers find out after signing; the state of the maintenance dues and the reserve fund, which in seafront buildings goes into façade upkeep and whether the tower holds a concession or permit for the beach in front, which does not come with the apartment.
- Ask the District what risk information it holds on the property and hand that to your insurance broker before asking for quotes.
Mistakes that cost money
- Assuming the building's policy covers the inside of the apartment. It insures common property, and your own contents fall outside it.
- Buying the lender's policy without reading what it covers. It protects the creditor's collateral, which is not the same as protecting you.
- Letting the certificate lapse and finding out at the moment of a loss. Ask the administrador for the renewal date and ask again each year.
Frequently asked questions
- Can I insure a serviced lot from abroad?
- Yes, through an insurer supervised in Colombia, arranged by email with a broker; payment and billing are coordinated with him.
- Who files the claim when the damage is to common property?
- The administración, under the association's policy. The owner claims his own loss under his own policy, which is why both should be identified before buying.
- Does the lender's policy work as my property insurance?
- It answers what the institution requires for its collateral. What is missing for you is a question for your broker, with the reglamento and the deed in front of him.
Where to check it
- Superintendencia Financiera de Colombia — whether a trust company exists and is supervised, before transferring money to a patrimonio autónomo
- Alcaldía Mayor de Cartagena de Indias — property tax, betterment levies and District procedures
- Cartagena de Indias — the rules of the municipality Morros belongs to
Official bodies. Specific figures are requested there, not copied from a listing.
Updated 2026-11-06
Interested in a property in this area?
Write to us and we will send you the available options.