Most foreign buyers assume the building is already insured and that this covers them. The association's policy and the owner's own policy cover different things, and between the two sits a gap that shows up on the day of a loss.
The association's policy covers the building's common property and the administrador takes it out against the budget; the owner's policy covers the private area, the contents and third-party liability, and you take that one out. For an aparta-estudio (studio unit) the boundary between them does not fall in the same place, and that is the exposure: what is bien común de uso exclusivo for one unit is private area for another, and a terrace, a boundary wall or an air-conditioning unit can end up outside both policies. Where there is a mortgage the lender also requires its own cover as a condition of disbursement, and charges it inside the instalment. Before signing any of them, confirm with the Superintendencia Financiera that the insurer is supervised, and before insuring anything, find out what risk information the District holds on that property.
An aparta-estudio, a single-room studio unit, is bought differently because it is the smallest unit in the tower, and that has consequences the floor plan does not show. Its coeficiente de copropiedad, the ownership share, is low, so its weight at the asamblea is low too; and in buildings made of identical units, decisions fall to whoever can assemble a crowd of small owners. Meanwhile several building costs are not shared by size but by occupancy: lifts, front desk, lobby, water, waste and wear on common areas all track how many people come and go, and a studio generates as much turnover as a large unit while contributing a far smaller share. The second consequence is the market. These units are bought almost entirely to rent out, so what the reglamento says about renting by the day is not a detail of use but a feature of the asset, since it defines who you can resell to. The third is physical: in a single room, kitchen, bathroom and ventilation share walls with neighbors, so whatever the copropiedad resolved about noise, extraction and quiet hours weighs more here than in a conventional apartment.
What you buy in Morros is not land but a private unit created by subdividing a single folio matriz, the parent registry record, and that changes the file. The chain of title on the land was settled once by the builder; what remains to review is the registered reglamento de propiedad horizontal, the condominium bylaws, any acta de asamblea, owners' meeting minutes, that amended them, and the coeficiente de copropiedad, the ownership share assigned to the unit, which governs both voting and billing. The counterparty differs from the undeveloped north as well: usually an individual owner living outside Cartagena, so closing depends on a power of attorney from that person, on a spouse's consent where it applies, and on the paz y salvo, a no-arrears certificate signed by the building manager, a document that does not even exist for rural land. Decisions here belong to the owners' assembly and the manager it appoints, not to a public office; the District and the curaduría urbana, the private licensing office, had their say when the tower was permitted. Internal infrastructure, from pumping to the generator and security, is private and funded by the budget that same assembly approves, so the minutes describe the property better than any tour.
What is specific to Morros
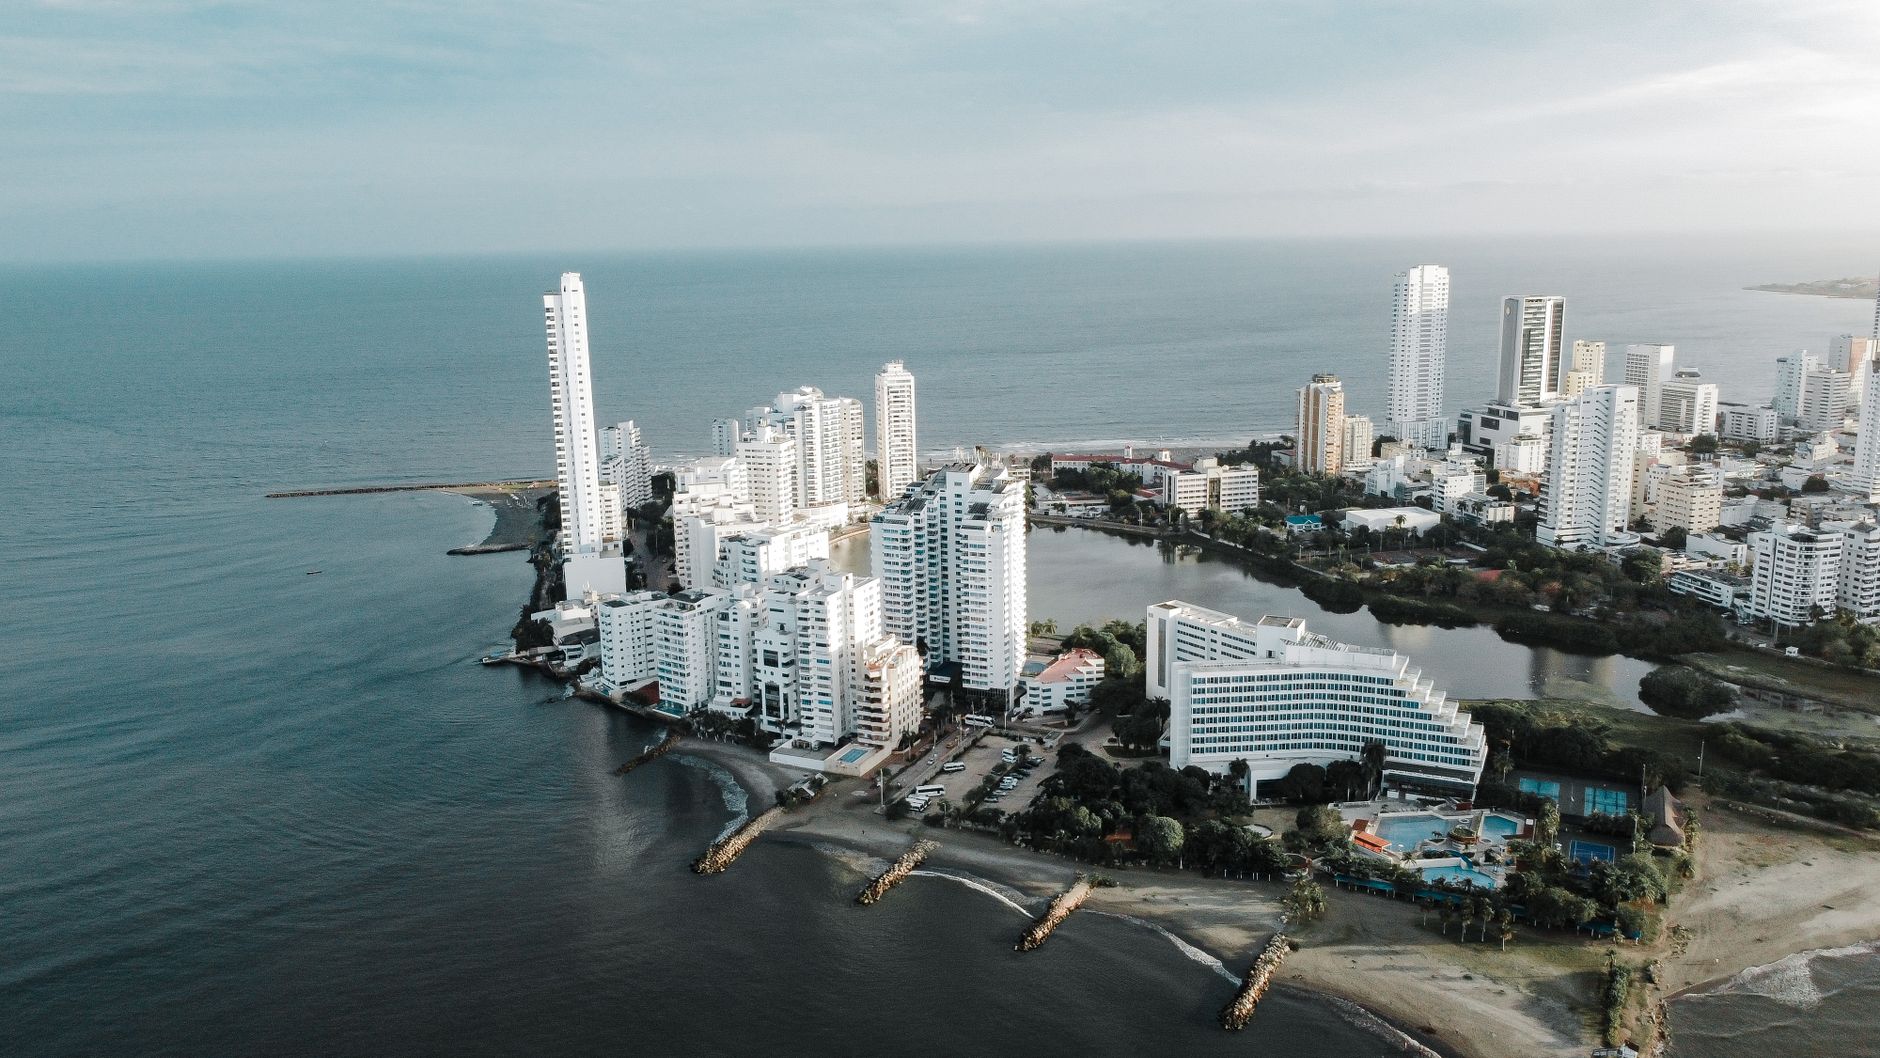
The first consolidated stretch of the Zona Norte: gated tower complexes along the road, beach in front and their own amenities. Almost everything is high-rise condominium, much of it bought as a second home and rented out seasonally. It sits minutes from the airport along the Anillo Vial, which is its only real way in and out.
- what the condominium bylaws say about daily rentals, because several complexes restrict them and buyers find out after signing
- the state of the maintenance dues and the reserve fund, which in seafront buildings goes into façade upkeep
- whether the tower holds a concession or permit for the beach in front, which does not come with the apartment
What to verify, step by step
- Ask the administrador for the current certificate of the association's policy, with its cover, exclusions and the insurer's name.
- Ask for the reglamento and the deed so you know where the unit's private area ends and common property begins, which is the line that decides which policy responds.
- Verify with the Superintendencia Financiera that the insurer and the intermediary are supervised before paying any premium.
- Review what has to be insured because it is aparta-estudio units: whether the reglamento de propiedad horizontal allows daily rentals, since this is the unit type most often bought for exactly that and the ban never shows up in the brochure; whether the deed places kitchen and bathroom inside the área privada rather than treating them as shared services that cannot later be enclosed and how many identical units the tower holds, and what the administración rules about lift and lobby use by short-stay guests.
- Add the exposures particular to Morros: what the condominium bylaws say about daily rentals, because several complexes restrict them and buyers find out after signing; the state of the maintenance dues and the reserve fund, which in seafront buildings goes into façade upkeep and whether the tower holds a concession or permit for the beach in front, which does not come with the apartment.
- Ask the District what risk information it holds on the property and hand that to your insurance broker before asking for quotes.
Mistakes that cost money
- Assuming the building's policy covers the inside of the apartment. It insures common property, and your own contents fall outside it.
- Buying the lender's policy without reading what it covers. It protects the creditor's collateral, which is not the same as protecting you.
- Letting the certificate lapse and finding out at the moment of a loss. Ask the administrador for the renewal date and ask again each year.
Frequently asked questions
- Can I insure an aparta-estudio (studio unit) from abroad?
- Yes, through an insurer supervised in Colombia, arranged by email with a broker; payment and billing are coordinated with him.
- Who files the claim when the damage is to common property?
- The administración, under the association's policy. The owner claims his own loss under his own policy, which is why both should be identified before buying.
- Does the lender's policy work as my property insurance?
- It answers what the institution requires for its collateral. What is missing for you is a question for your broker, with the reglamento and the deed in front of him.
Where to check it
- Superintendencia Financiera de Colombia — whether a trust company exists and is supervised, before transferring money to a patrimonio autónomo
- Alcaldía Mayor de Cartagena de Indias — property tax, betterment levies and District procedures
- Cartagena de Indias — the rules of the municipality Morros belongs to
Official bodies. Specific figures are requested there, not copied from a listing.
Updated 2026-11-06
Interested in a property in this area?
Write to us and we will send you the available options.