Most foreign buyers assume the building is already insured and that this covers them. The association's policy and the owner's own policy cover different things, and between the two sits a gap that shows up on the day of a loss.
The association's policy covers the building's common property and the administrador takes it out against the budget; the owner's policy covers the private area, the contents and third-party liability, and you take that one out. For a beach lot the boundary between them does not fall in the same place, and that is the exposure: what is bien común de uso exclusivo for one unit is private area for another, and a terrace, a boundary wall or an air-conditioning unit can end up outside both policies. Where there is a mortgage the lender also requires its own cover as a condition of disbursement, and charges it inside the instalment. Before signing any of them, confirm with the Superintendencia Financiera that the insurer is supervised, and before insuring anything, find out what risk information the District holds on that property.
A beach lot is bought differently because the first question is not what you may build but whether a private owner ever existed. Along the coastal strip you find land that could lawfully be granted, land that never left the public domain, and land someone occupied and then transferred without holding the right, so the chain of title may rest on mere possession or on falsa tradición, a transfer by someone who never held registered ownership. No deed, no notaría and no lapse of time fixes that, because property in the public domain cannot be acquired by prescription. Investigating the origin of title therefore outranks everything else and comes before any other conversation. The second difference is that the object itself moves: the shoreline advances or retreats, and the area shown on the folio may not be the land that is dry today. The third is that a substantial part of the terrain is not buildable at all, between the public strip, the ronda hídrica (protected water margin) and environmental setbacks, so the usable lot is always smaller than the lot purchased, and it is worth fixing that with a survey and with the environmental authority.
Bocagrande works like a mature resale market, with consequences that do not repeat up north. The counterparty is almost never a builder: it is a long-standing owner or, very often, an unsettled sucesión, an estate proceeding, whose heirs live in different countries, so closing depends not on one power of attorney but on several, and on the partition among them. The registry record is old too: it was opened when the building was submitted to the condominium regime, it carries legacy entries such as cancelled mortgages, patrimonio de familia and afectación a vivienda familiar, both family-home protections, or lifted attachments, and the recorded area does not always match a current survey, so you compare the registry record against the deed and against the unit's floor plan. The peninsula is also land reclaimed from the sea under subdivisions the District authorized in their day, and the oldest deeds still carry references to those parcelaciones, the original platting. Day-to-day power sits with the owners' assembly and its manager, so in a tower with a long record of decisions the minutes and the status of the condominium's lawsuits matter more than the brochure.
What is specific to Bocagrande
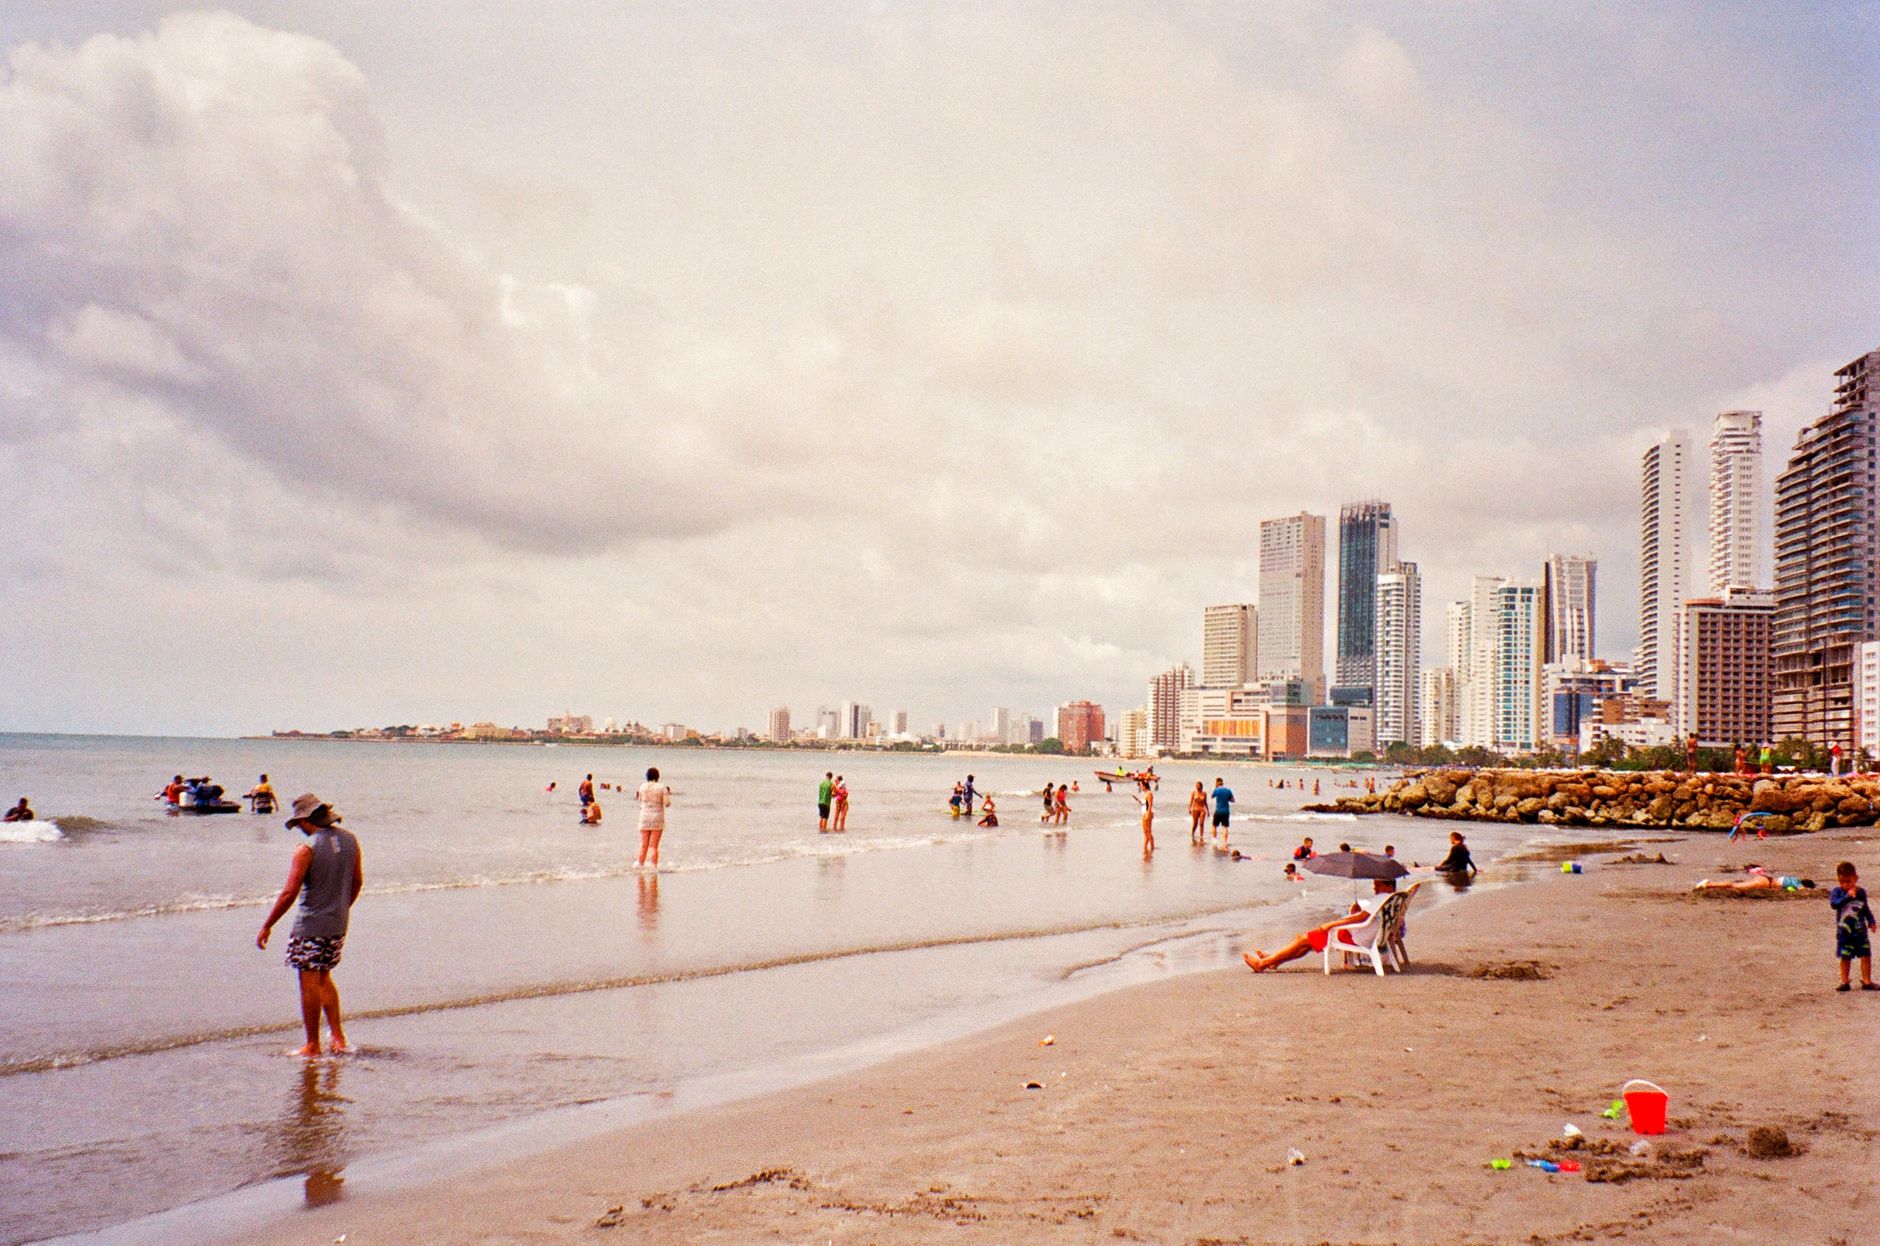
Cartagena's dense, vertical peninsula: open sea on one side, bay on the other, and built out to the last lot. Condominium towers from very different eras, from the sixties to recent construction, on the same block. Groceries, restaurants and beach are walkable, and access is through a few roads that saturate in high season.
- the building's actual age and whether it has a structural vulnerability study, since much of the stock was built under seismic codes earlier than those now in force
- what the condominium bylaws say about daily rentals, which on this peninsula is the difference between being able to rent and not
- how many parking spaces the unit holds in the deed, not in the brochure, because older towers do not have one per apartment
What to verify, step by step
- Ask the administrador for the current certificate of the association's policy, with its cover, exclusions and the insurer's name.
- Ask for the reglamento and the deed so you know where the unit's private area ends and common property begins, which is the line that decides which policy responds.
- Verify with the Superintendencia Financiera that the insurer and the intermediary are supervised before paying any premium.
- Review what has to be insured because it is beach lots: where the zona de bajamar ends: it is public domain of the Nation, cannot be sold, and no private deed cures it; whether the lot has its own matrícula inmobiliaria or was never split out, and whether the chain of title carries falsa tradición (a transfer by someone who never held registered ownership) or mere possession and how much of the lot is actually buildable once the public strip, the ronda hídrica (protected water margin) and the environmental setback are taken out.
- Add the exposures particular to Bocagrande: the building's actual age and whether it has a structural vulnerability study, since much of the stock was built under seismic codes earlier than those now in force; what the condominium bylaws say about daily rentals, which on this peninsula is the difference between being able to rent and not and how many parking spaces the unit holds in the deed, not in the brochure, because older towers do not have one per apartment.
- Ask the District what risk information it holds on the property and hand that to your insurance broker before asking for quotes.
Mistakes that cost money
- Assuming the building's policy covers the inside of the apartment. It insures common property, and your own contents fall outside it.
- Buying the lender's policy without reading what it covers. It protects the creditor's collateral, which is not the same as protecting you.
- Letting the certificate lapse and finding out at the moment of a loss. Ask the administrador for the renewal date and ask again each year.
Frequently asked questions
- Can I insure a beach lot from abroad?
- Yes, through an insurer supervised in Colombia, arranged by email with a broker; payment and billing are coordinated with him.
- Who files the claim when the damage is to common property?
- The administración, under the association's policy. The owner claims his own loss under his own policy, which is why both should be identified before buying.
- Does the lender's policy work as my property insurance?
- It answers what the institution requires for its collateral. What is missing for you is a question for your broker, with the reglamento and the deed in front of him.
Where to check it
- Superintendencia Financiera de Colombia — whether a trust company exists and is supervised, before transferring money to a patrimonio autónomo
- Alcaldía Mayor de Cartagena de Indias — property tax, betterment levies and District procedures
- Cartagena de Indias — the rules of the municipality Bocagrande belongs to
Official bodies. Specific figures are requested there, not copied from a listing.
Updated 2026-11-06
Interested in a property in this area?
Write to us and we will send you the available options.