Most foreign buyers assume the building is already insured and that this covers them. The association's policy and the owner's own policy cover different things, and between the two sits a gap that shows up on the day of a loss.
The association's policy covers the building's common property and the administrador takes it out against the budget; the owner's policy covers the private area, the contents and third-party liability, and you take that one out. For a beachfront house the boundary between them does not fall in the same place, and that is the exposure: what is bien común de uso exclusivo for one unit is private area for another, and a terrace, a boundary wall or an air-conditioning unit can end up outside both policies. Where there is a mortgage the lender also requires its own cover as a condition of disbursement, and charges it inside the instalment. Before signing any of them, confirm with the Superintendencia Financiera that the insurer is supervised, and before insuring anything, find out what risk information the District holds on that property.
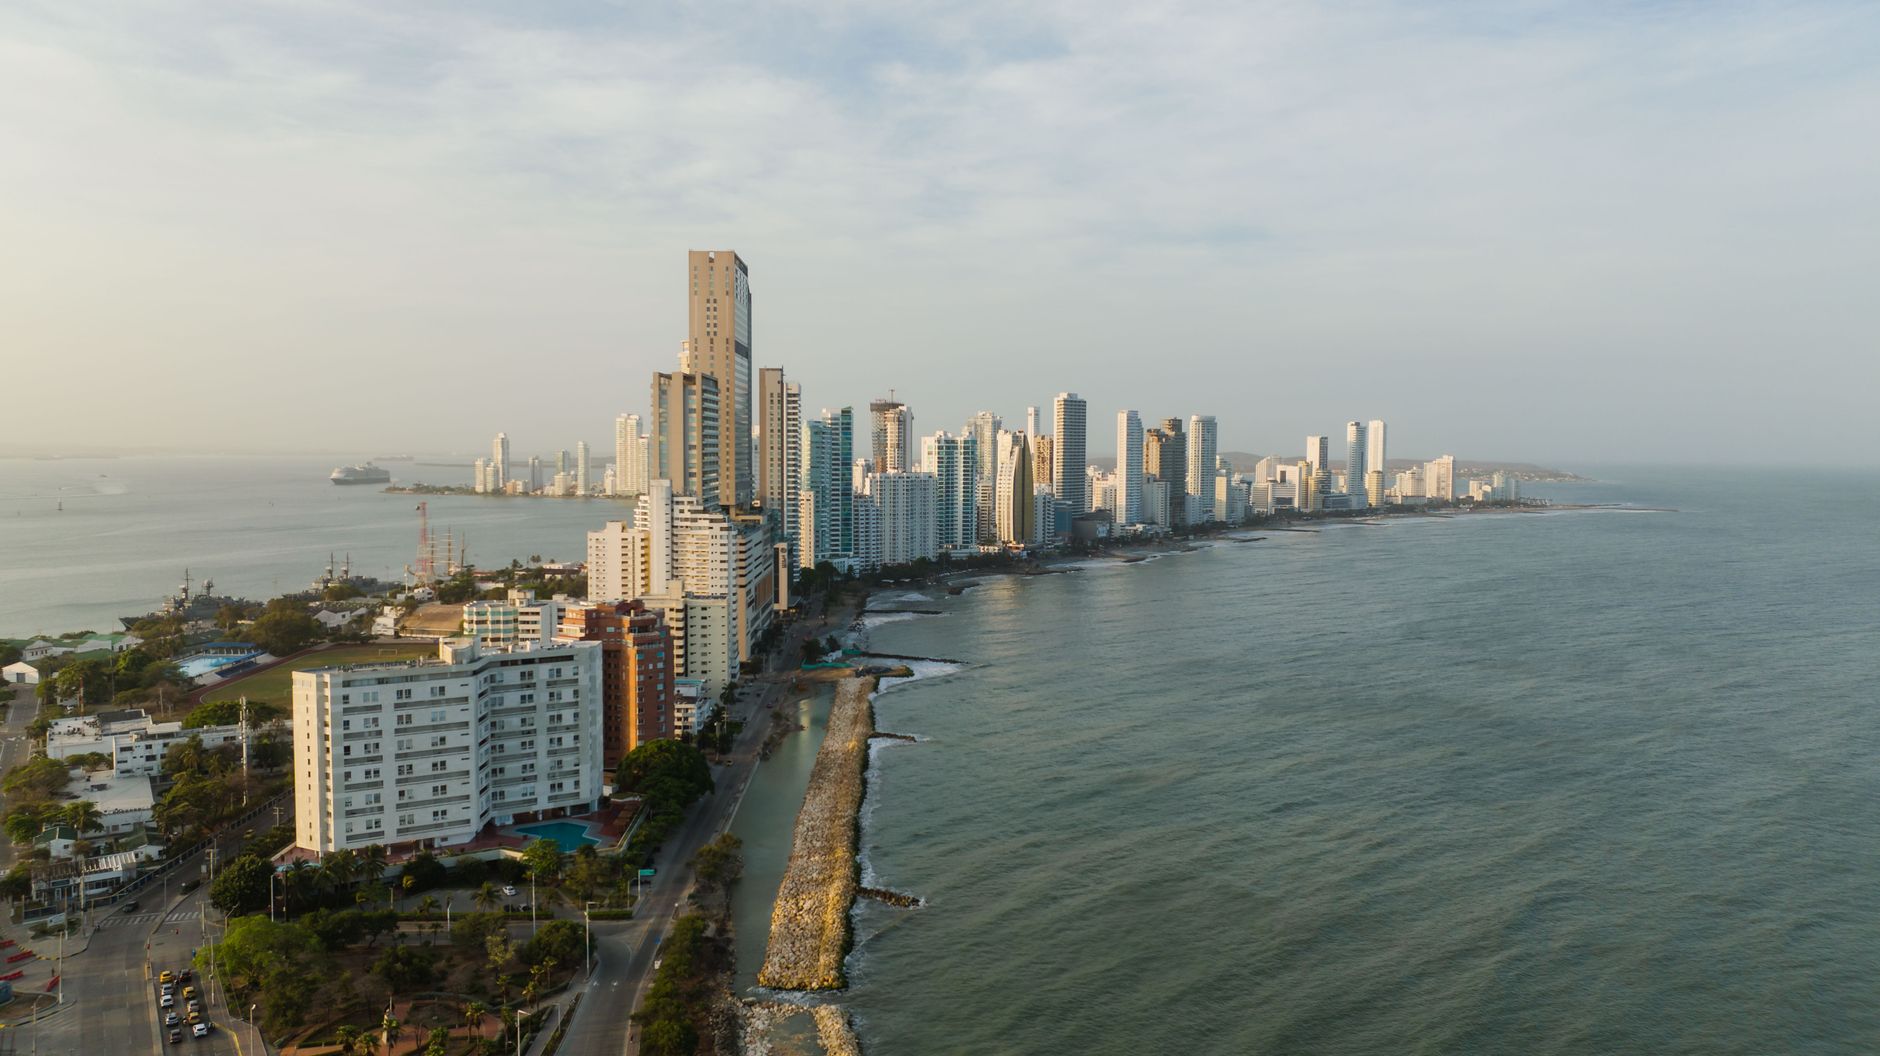
A beachfront house is bought differently because one of its boundaries was not drawn by a surveyor: the water draws it and the State defines it. In front of the lot lies a strip that is bien de uso público of the Nation —public domain— which cannot be sold, fenced or acquired by the passage of time. So part of what you enjoy from the terrace will never belong to anyone, and the public keeps its right of access. That condition reshapes the whole review. A clean deed and a clean folio are not enough: you need to know where that line sits today, whether any structure on the lot crossed it, and whether a proceeding is open before the maritime or environmental authority, because building on public land is not cured with money or at a notaría. The second point is that the property lives inside a medium that attacks it. Salt air and surf work on the structure year round, so what you buy includes maintenance that never pauses and, very often, a coastal protection work whose owner and whose duty to repair are worth identifying before signing, especially when it sits outside the boundary or is shared with neighbors.
In Castillogrande the typical deal is not a unit in a condominium but a house and its lot, which puts the weight of the file back on the chain of title to the land: you climb through the deeds to the parcelación, the original subdivision that created the block, because those platting deeds registered conditions, setbacks and easements that still bind and that are invisible from the street. There is no building manager to issue a paz y salvo, a no-arrears certificate, and no assembly to settle anything, so boundary questions with a neighbor are argued between private parties and what governs is the title and the survey, not a set of house rules. The counterparty is usually an old city family and, fairly often, a family company that owns the property: then you must decide whether to buy the real estate or the company's shares, two different transactions with different paperwork and different exposure, and request the certificado de existencia y representación, the corporate good-standing and signing-authority certificate, together with the resolution approving the sale. And because the neighborhood is fully built out, any construction is permitted on an already developed lot, with neighbors entitled to take part in the proceeding.
What is specific to Castillogrande
The residential tip of the peninsula: lower and quieter than Bocagrande, facing the bay, with little street retail. Houses and low-rise buildings sit alongside new towers, and single-family homes still exist. It is a dead end: access is through Bocagrande with no through road at the far tip, which keeps it free of passing traffic.
- whether the property faces the bay or the open sea, because the swell, the smell and the façade upkeep are not comparable
- what building height the rules allow on the lot, which is not uniform across the peninsula and is the first fact omitted when a lot is sold
- how ground stability was addressed, given this is land reclaimed from the sea, and what the soil study for the building says
What to verify, step by step
- Ask the administrador for the current certificate of the association's policy, with its cover, exclusions and the insurer's name.
- Ask for the reglamento and the deed so you know where the unit's private area ends and common property begins, which is the line that decides which policy responds.
- Verify with the Superintendencia Financiera that the insurer and the intermediary are supervised before paying any premium.
- Review what has to be insured because it is beachfront houses: where the zona de bajamar (the tidal strip, public domain of the Nation) ends in front of the lot, because nothing built on it conveys with the house; whether the fence, pool or terrace encroach on that strip, and whether any proceeding is open before the maritime or environmental authority and how wave protection was solved and who owns the protection works, which often sit outside the boundary line.
- Add the exposures particular to Castillogrande: whether the property faces the bay or the open sea, because the swell, the smell and the façade upkeep are not comparable; what building height the rules allow on the lot, which is not uniform across the peninsula and is the first fact omitted when a lot is sold and how ground stability was addressed, given this is land reclaimed from the sea, and what the soil study for the building says.
- Ask the District what risk information it holds on the property and hand that to your insurance broker before asking for quotes.
Mistakes that cost money
- Assuming the building's policy covers the inside of the apartment. It insures common property, and your own contents fall outside it.
- Buying the lender's policy without reading what it covers. It protects the creditor's collateral, which is not the same as protecting you.
- Letting the certificate lapse and finding out at the moment of a loss. Ask the administrador for the renewal date and ask again each year.
Frequently asked questions
- Can I insure a beachfront house from abroad?
- Yes, through an insurer supervised in Colombia, arranged by email with a broker; payment and billing are coordinated with him.
- Who files the claim when the damage is to common property?
- The administración, under the association's policy. The owner claims his own loss under his own policy, which is why both should be identified before buying.
- Does the lender's policy work as my property insurance?
- It answers what the institution requires for its collateral. What is missing for you is a question for your broker, with the reglamento and the deed in front of him.
Where to check it
- Superintendencia Financiera de Colombia — whether a trust company exists and is supervised, before transferring money to a patrimonio autónomo
- Alcaldía Mayor de Cartagena de Indias — property tax, betterment levies and District procedures
- Cartagena de Indias — the rules of the municipality Castillogrande belongs to
Official bodies. Specific figures are requested there, not copied from a listing.
Updated 2026-11-06
Interested in a property in this area?
Write to us and we will send you the available options.